Let’s talk about balance sheet structure, starting with a focus on Assets.
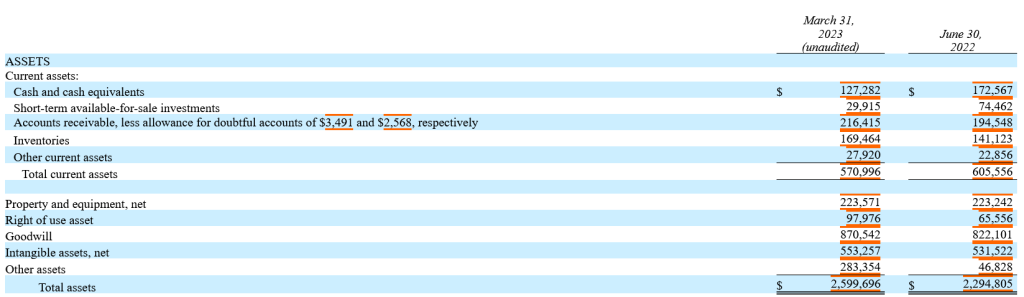
Below is the balance sheet for our exemplar company, BioTechne:

The first part of the balance sheet is a list of the company’s assets, shown below:
Assets are what the company owns: cash and securities, equipment, inventory, intellectual property (IP), real estate, ‘goodwill’ (stay tuned), anything a company could use to create economic value for its customers.
Life science asset examples
Now let’s steer this toward life sciences— what kind of assets would a life sciences company have?
Taking a look at the BioTechne balance sheet, we see (balance sheet language is in parentheses):
- cash on hand (cash and cash equivalents),
- inventory ready to sell (short-term available-for-sale investments),
- cash they’re owed from customers (accounts receivable),
- inventory that is either raw materials or in the process of being made, or products ready for sale (inventories),
- physical assets the company owns (property and equipment, net),
- assets the company is leasing (Right of use asset),
- difference between the physical assets of an acquired company and what the acquiring company paid; reputation, customer base, and other so on- see below (Goodwill),
- non-physical assets like employees skills, customer lists and relationships, proprietary knowledge, patents, reputation, data, etc. (intangible assets),
- anything else the company owns (other assets),
In the balance sheet asset section, you can see there are two chunks of numbers.
If assets are either cash, or we expect to turn them into cash in a year or less, then we call them “current assets”. These are in the first block of figures.
If, however, the assets will not turn into cash in a year or less, they are called “noncurrent assets”, although they are not called out as such in the BioTechne balance sheet.
Clearly cash and cash equivalents are already cash. They’re current assets.
Accounts receivable, or the cash we’re owed from our customers, are current assets. We expect to collect that cash within a year.
Likewise inventories, the stuff we have on shelves, are current assets, since we expect to sell it and collect within a year.
On the other hand, property and equipment, goodwill, and intangible assets will not be monetized within a year, so it’s a noncurrent asset.
Making sense of balance sheet’s ‘Goodwill’ assets
Before we move on to liabilities and equity, let’s talk about Goodwill and Intangible Assets (which includes IP generated by R&D).
Goodwill can be defined as “difference between the physical assets of an acquired company and what the acquiring company paid; reputation, customer base, and other so on.”
Let’s give this definition a little more concreteness with a hypothetical example, shall we? We know from reading other parts of the 10-K that BioTechne acquired Exosome Diagnostics in 2018. A little digging reveals that BioTechne paid $250 million in cash plus contingent consideration of up to $325 million due upon the achievement of certain future milestones. When this happened, the asset called ‘cash’ decreased by $250M, and, in order for the balance sheet to balance, all other assets have to rise by $250M; so far nothing has happened that would change liabilities or owners’ equity.
So what assets increase? Well, you have the physical assets that BioTechne got with this acquisition— physical things that can be sold. Maybe some lab equipment, servers or other computer equipment, perhaps even the physical lab space. These assets are not likely to constitute the bulk of the $250M cash up-front that BioTechne paid. In fact, the CEO at the time said, ““ExosomeDx’s technology is a game changer and positions Bio-Techne to be a leader in the rapidly growing noninvasive liquid biopsy market.” And a Fierce Biotech article at the time stated, “With the deal, Bio-Techne is also getting about 200 of Exosome’s filed patents and applications of technology focused on new diagnostics in various pathologies with either difficult or no current diagnostic solutions, such as prostate, bladder, kidney, breast, glioblastoma and other cancers.” In other words, quite a lot of the value the BioTechne expected to get out of the ExosomeDx acquisition (at least publicly) was in (1) market positioning and (2) intellectual property, proprietary knowledge, and employee skills. Except for the patents, which could potentially be sold, these items fall into the bucket of ‘Goodwill.’
As you are probably gathering, goodwill is a bit squishy and too much of it on a balance sheet is probably a signal to be a bit wary. This is particularly true as goodwill is not amortized, so unlike the physical items gained in the acquisitions, which will depreciate over time, goodwill assets will continue to sit on the books.
IP, patents, and other intangible assets are an important aspect of the balance sheet for anyone leading an R&D organization to understand. Consider: how do you account for the cost of creating a new asset, like a reagent kit or clinical assay, that you expect to generate revenue for years to come? Just like we saw with depreciation in the income statement section, you don’t record the whole cost upfront, as it will generate revenue over time (remember in the income statement you are trying to abide by the ‘Matching Principle’). If you choose to amortize your R&D, then your assets and profitability will look better in the short term (just like the example of depreciation we worked through in a previous section). A more conservative approach is to expense R&D as it is incurred. So as we saw with depreciation in physical assets, there is room for shenanigans with intangible assets as well that impact both equity on the balance sheet and profitability on the income statement.
In the next part of this series, we’ll cover the liabilities and equity side of the balance sheet. You can sign up here to join the mailing list so you don’t miss it.