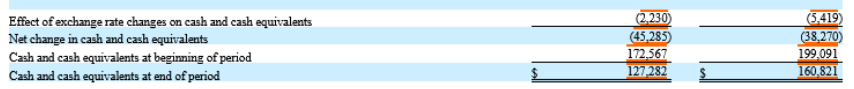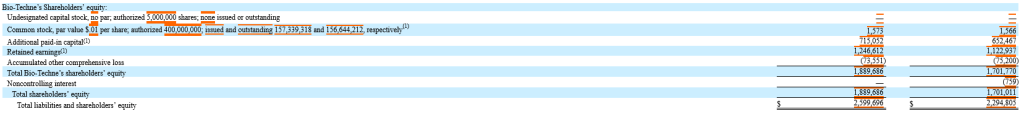
Well folks, we really saved the best for last here. In our final post on Finance for Scientists, we’ll be talking about one of the single most valuable tool I have learned in my adventures in finance: Net Present Value.
Why is NPV such a helpful concept for scientists? Because this tool is used by your business and finance counterparts to decide whether a particular project is worth pursuing. It is used to answer the question: relative to the low risk option of holding onto the cash needed to fund a given new project, how much money could this project generate over a particular time horizon? Understanding how NPV is calculated can not only help you make better sense of your company’s decisions, it can also help you structure projects in such a way as to make them more likely to be palatable to upper management (play around with these tools a bit and you will have a whole new appreciation for why timelines are so important.)
So what is NPV?
Net Present Value (NPV) is a way of measuring how much money an investment will generate in the future, compared to how much it costs today. NPV takes into account the time value of money, which means that a dollar today is worth more than a dollar tomorrow, because you can invest it and earn interest.
NPV is a powerful tool and the finance professional’s first choice for analyzing capital expenditures. There are three key reasons for this:
- It takes into account the time value of money. Future cash flow is discounted to understand their value in today’s dollars.
- It considers a business’s cost of capital or other hurdle rate. Cost of capital is the return expected by those who provide capital for the business. Hurdle rate is the minimum acceptable rate of return investors use to analyze profitability when evaluating a potential investment. In other words, NPV takes into account the specific situation of the business (which you will see shortly includes current interest rates).
- It provides an answer in today’s dollars, allowing you to compare the initial cash outlay with the present value of the return.
So, to calculate NPV, you need to estimate the future cash flows (inflows and outflows) of the investment, and discount them by a certain rate that reflects the risk and opportunity cost of the investment. The discount rate is usually based on the cost of capital or the expected return of similar investments. The NPV is the sum of all the discounted cash flows.
The discounting equation looks like this:
PV = FV1/(1+i) + FV2/(1+i)2 + … + FVn/(1+i)n
PV = Present Value
FV = projected cash flow for each time period
i = discount or hurdle rate
N = number of time periods (typically years in biotech/diagnostics) you are looking at
NPV = PV – initial cash outlay
For example, suppose you want to invest in a new diagnostic device for a rare disease. You estimate that the device will cost $10 million to develop and launch, and will generate $2 million per year for 10 years. You also estimate that the discount rate for this project is 10%, which means that you expect to earn 10% per year on average from similar investments.
To calculate the NPV, you need to discount each cash flow by 10% per year.
So, for the first year, the discounted cash flow is:
$2 million / (1 + 0.1) ^ 1 = $1.82 million
For the second year, it is:
$2 million / (1 + 0.1) ^ 2 = $1.65 million
And so on, until the tenth year:
$2 million / (1 + 0.1) ^ 10 = $0.77 million
The NPV is the sum of all these discounted cash flows, minus the initial cost of $10 million:
NPV = ($1.82 million + $1.65 million + … + $0.77 million) – $10 million
NPV = $3.17 million
This means that investing in this device will generate a net profit of $3.17 million in today’s dollars, after accounting for the time value of money and the risk of the project.
However, this calculation assumes that the cash flows are certain and constant, which is rarely the case in reality. In practice, there are many uncertainties and risks involved in developing and launching a new diagnostic device, such as regulatory approval, market demand, competition, pricing, reimbursement, etc. These factors can affect both the amount and timing of the cash flows.
To account for these uncertainties and risks, some analysts use a modified version of NPV called risk-adjusted NPV (r-NPV). r-NPV adjusts each cash flow by multiplying it by a probability factor that reflects the likelihood of achieving that stage of development or commercialization. The probability factor is usually based on historical data or expert opinion.
Interest and Discount Rates vs. Your Research Project
Let’s talk briefly about interest rates and their impact on discount rates. Having never taken an economics class before, my mind was blown the first time someone walked me through this information, and it certainly has helped me better understand our current macroeconomic headwinds and Wall Street’s collective obsession with interest rates.
Higher interest rates mean a higher opportunity cost for funds. If your CFO uses a hurdle rate of 20%, it means she is pretty darn confident she can get almost that much return elsewhere for a similar level of risk. A high hurdle rate then sets a very high bar for new investments. When interest rates are high, there is always the low risk option of just sitting on your cash and still getting a pretty attractive return. So high interest rates increase the bar for investment. Similarly, if you need to raise capital to invest in this new opportunity, the cost of that capital will be higher due to the higher interest rates.
Conversely, if interest rates are very low, almost everything is better than sitting on your cash, so there is pressure for growth and investment. This situation was responsible for the halcyon days of 2019-2021. But as we are seeing now, because time scales are long in the biotech and life sciences sector, companies can get caught out by assuming that low interest rate/cost of capital days will last forever. And we are seeing this situation play out now as companies jettison development programs in order to preserve cash in the current economy (i.e., the discount rate has changed, so NPV calculations done in 2021 likely do not hold in 2024, and some opportunities are no longer worth pursuing— another reason why everyone likes shorter project timelines).
In summary, interest rates and NPV have the following relationship:
- As the interest rate increases, NPV decreases, and the bar for what a good investment is increases
- As the interest rate decreases, NPV increases, and the bar for what a good investment is decreases
One other important factor for scientists to consider in NPV calculations (which WILL be used to evaluate whether your pet project is worthwhile), is how the cost of the project is being estimated and how the projected cash flow is being estimated.
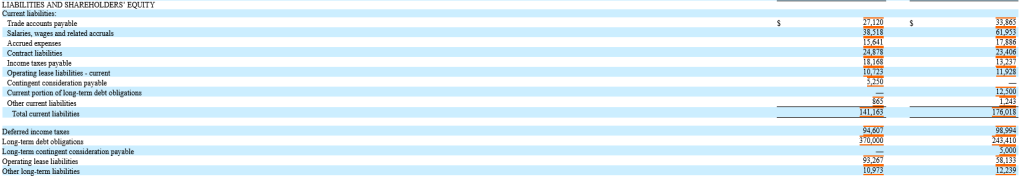
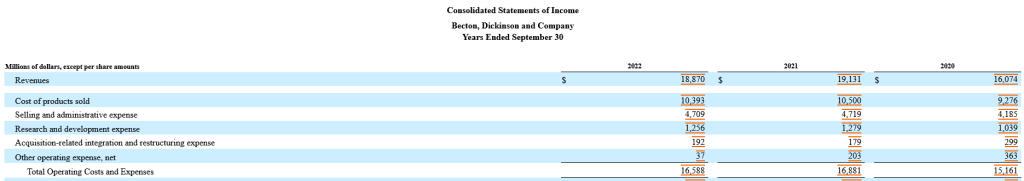
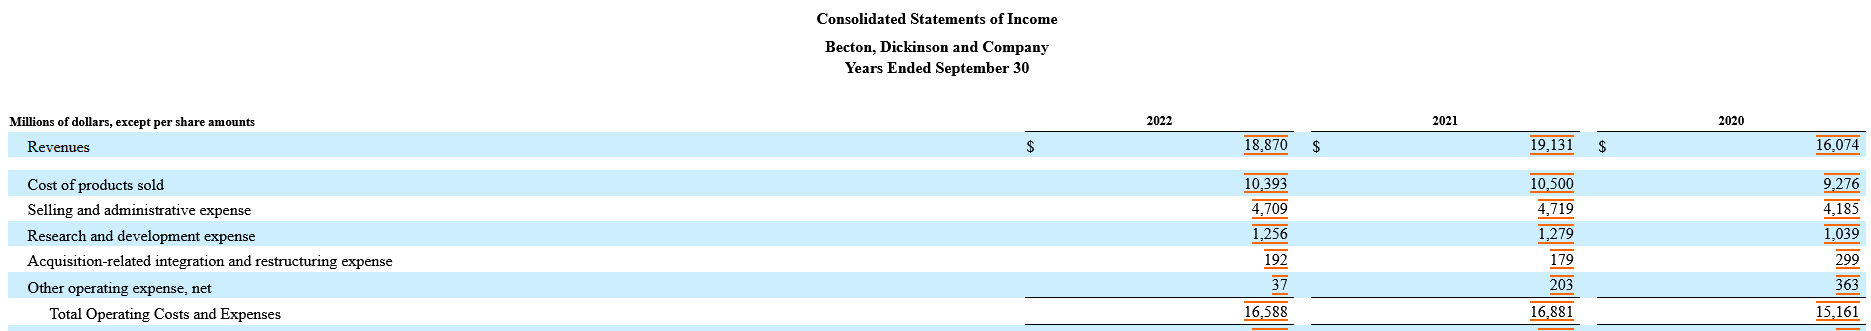
To do that, let’s go all the way back to the beginning of this series and think about the income statement. To refresh your memory, below is our favorite BioTechne example:

Many of the line items here will be used to estimate projected returns, so you need to know how your particular project is being ‘burdened,’ for example, with SG&A.
Quick example: let’s say you are developing a new product that runs on top of an existing platform. It will require some R&D investment, but because you are leveraging an existing platform, those costs are smaller than a new product that requires a totally new platform to be built. So your initial cash outlay will be smaller. Similarly, operating costs associated with running something on an existing platform will be relatively low (and scale with product volume). As a result, as you are calculating your projected cash flow, you would want to include some incremental operating costs in the first years after launch that then scale with sample volume. Conversely, if this new product requires building out a new sales and marketing team, those expenses can dramatically decrease the return expected in the early years after launch. However, if you are creating a new offering for an existing sales channel, then your returns will be higher. G&A can usually be approximated as a percentage of overall volume.
All of these details will be important to understand as you are thinking about starting a new line of research, and then to consider more carefully (and this part is usually led by finance) when putting together the business case. Having your own understanding about these calculations can help you challenge assumptions that your finance team may be making that cause the business case to look significantly worse than it ought to. Similarly, as a savvy scientist, you can perhaps think about ways to decrease the upfront spend or brainstorm with your business development and marketing colleagues on alternative routes to revenue in the early days post product launch (can you reach some customer segments through existing channels? Are there channels that have lower regulatory or reimbursement requirements that can be accessed sooner? etc.). And by running a minimal NPV analysis for yourself in the initial concept phase of projects, you can get a feel for the likelihood of eventual success and prioritize your efforts accordingly.
I could probably write another 3 posts on NPV, if this topic is of sufficient interest to folks (reach out in the comments).
Otherwise, I will leave you with a few useful resources as I close out the final planned post of this series!
Thanks for following along! And a big thank you to Jeff Krimmel for inspiration and the authors of Financial Intelligence. A Manager’s Guide to Knowing What the Numbers Really Mean (Karen Berman and Joe Knight) for their easy-to-read book on finance!