

“Cash is king,” or so they say. Let’s see how this plays out in the Cash Flow Statement.
We’ve already covered two of the three foundational financial statements— the balance sheet and the income statement.
The balance sheet told us about what the business owns, and what it owes. We use that information to understand the potential to create value for customers.
The income statement told us about the profitability of the business, or how much it costs to generate each dollar of revenue.
Let’s now turn to the third and final foundational financial statement.
The Cash Flow Statement
The cash flow statement is a recording of all the cash that entered and left the business over a period of time. It’s also the financial statement least subject to biases that creep in due to assumptions and estimates. The famous investor Warren Buffet is known to put the greatest emphasis on the cash flow statement when he examines financial statements, paying particular attention to ‘owner earnings.’ The owner earnings (also known as “Free Cash Flow”) can be calculated directly from the cash flow statement by finding the difference between the operating activities and the capital expenditures (i.e., the cash flow from investing activities).
The cash flow statement can provide insight into the financial health and status of an organization.
Specifically, by looking at the cash flow statement, we can answer the following kinds of questions:
- What is the liquidity situation of the company (i.e., what can be readily converted to cash)?
- What are the company’s sources of cash?
- Is there free cash flow being generated to further invest in assets or operations?
- Is the overall cash increasing or decreasing? How stable is it across different time frames?
The cash flow statement has an important structure. Below is the cash flow statement for BioTechne:

You can see in this example that there are three sections.
- The first part describes cash flow from operating activities— cash flow that’s generated once the company delivers its regular goods or services
- The second part is cash flow from investing activities— cash flow from purchasing or selling assets (both physical and non-physical property) using cash, not debt (sometimes referred to as capital expenditures)
- The third part is cash flow from financing activities— cash flow from both debt and equity financing
Finally, there is a summary section at the bottom that looks like this:
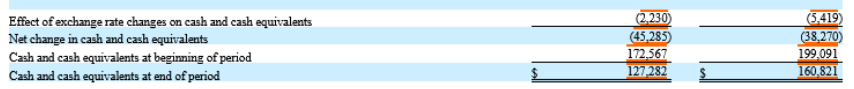
This section tells us whether BioTechne is cash flow positive or negative in the ‘Net change in cash and cash equivalents’ line. So in both 2022 and 2023, BioTechne was cash flow negative, meaning the cash outflow was higher than the cash inflow during that period.
Cash flow vs. profit
Negative cash flow doesn’t necessarily mean profit is lost. Instead, negative cash flow may be caused by a company’s decision to expand the business and invest in future growth. It can also indicate an expenditure and income mismatch, which should be addressed as soon as possible. Similarly, positive cash flow, while ideal, does not necessarily translate to profit. A business can be profitable without being cash flow-positive, and can have positive cash flow without actually making a profit (often through borrowing money).
Here it’s important to remember that profit is typically defined as the balance that remains when all of a business’s operating expenses are subtracted from its revenues, it answers the question: how much money is left over from selling a product after all expenses from producing it have been paid? This is fundamentally a different question than what cash flow answers, which centers more around whether a company has enough liquidity or cash to pay its expenses.
In a nutshell, this is why it’s important to look at financial statements together.
We’ll dig in more to the three sections of the cash flow statement in our next post. Stay tuned with via the mailing list for updates!