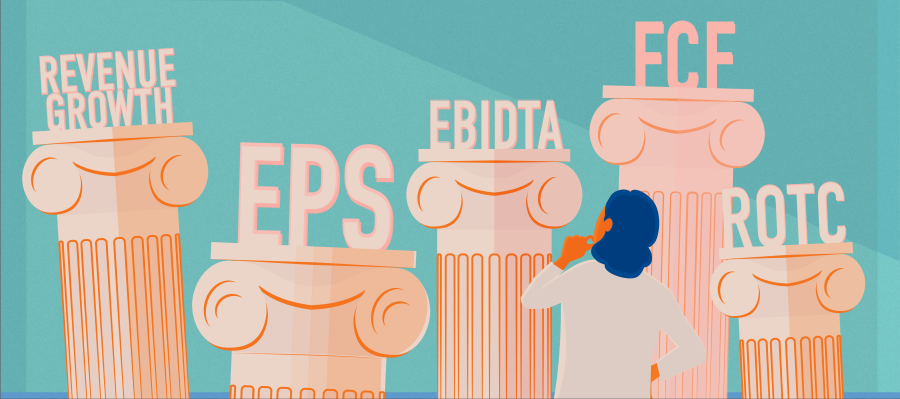
In this post, we cover the ratios and other financial indicators Wall Street or other outside investors care about. These ratios can have a large impact on managerial decisions, because companies generally need to keep shareholders and investors happy and how well leadership does in this endeavor will impact stock price, which in turn influences the success of a company.
Here are the ‘Big Five’:
- Revenue Growth
- Earnings per Share (EPS)
- Earnings Before Interest, Taxes, Depreciation, and Amortization (EBIDTA)
- Free Cash Flow (FCF)
- Return on Total Capital (ROTC)
Let’s dive deeper.
Revenue Growth
This metric measures how fast the company is increasing its sales over a period of time. A high revenue growth rate indicates that the company has a strong demand for its products or services, and that it can scale up its operations. No investor is going to put money in a company where the value of their investment will stay flat or decrease over time (okay— well there are really sneaky things people do with the intention of decreasing their tax liability, but we’ll set that aside for now). If a company wants to be successful, they need to show the potential for growth.
Earnings per Share (EPS)
First up is EPS, which we encountered in the last post on Earnings Calls. This metric measures the profitability of a company by dividing its net income by the number of outstanding shares. EPS reflects the earnings potential of a company and its ability to generate returns for shareholders. All other things being equal, a growing EPS portends an increase in stock price. In an economic slowdown, companies will work hard to keep EPS up by reducing costs (not always great for the humans working at these companies). Shareholders can accept revenue decline, but are unhappy to see a decrease in EPS.
Earnings Before Interest, Taxes, Depreciation and Amortization (EBITDA) margin
This metric measures how much of the revenue is left after deducting the operating expenses, excluding interest, taxes, depreciation and amortization. A high EBITDA margin indicates that the company has a high profitability and cash flow generation; it’s a good indicator of future operating cash flow. EBIDTA is also often used in valuing a business, as a company’s sale price is often negotiated as a multiple of EBIDTA.
Free Cash Flow (FCF)
This metric measures the amount of cash that a company generates from its operations after deducting capital expenditures. FCF indicates the financial flexibility of a company and its capacity to invest in growth opportunities, pay dividends, reduce debt, or repurchase shares. In this economic climate, it’s especially important, as a company with a healthy free cash flow can continue to fund its own growth even when investment dollars are hard to come by.
Note that EBIDTA and FCF can be used together to understand how well a company is doing at converting profit to cash, by taking the ratio of FCF divided by EBIDTA. When this ratio is low, it can mean that a company is trying to make EBIDTA look strong through gimmickry even while its cash flow is weak.
Return on Total Capital (ROTC)
This metric measures a company’s net income relative to the sum of its debt and equity value, or the efficiency with which invested funds are used in a business. Essentially it helps investors understand whether a business is generating a return high enough to justify their investment.
More terms of interest
A few other metrics investors care about: Market Cap, Price-to-Earnings, and Shareholder Value
Market Cap
Market cap is simply the current stock price of a company multiplied by the number of shares outstanding, which appears on the balance sheet under Capital Stock. This metric shows a snapshot of what the company is worth to investors. Savvy investors like Warren Buffett will look at the ratio of the market cap to the ‘book value,’ or the value of the equity as shown on the balance sheet. It is said that Buffett tries to find and invest in companies that are trading at market cap close to or below their book value, as this situation may indicate that a company is undervalued (note: another thing that is said about Buffett is that he invests only in businesses he understands, so I would imagine there is an element of critical thinking in determining whether the business is actually undervalued… also note, this strategy is inherently banking on the market eventually recognizing the value of a company in the LONG TERM).
Price-to-Earnings
This metric is the current stock price divided by the prior year’s earning per share, and measures how much the market is willing to pay for each unit of earnings. Companies with higher ratios are considered to have high growth potential.
Shareholder Value
This term does not point to any single concrete metric— in fact, every ratio discussed could be said to indicate ‘shareholder value.’ But regardless of the specific definition, increasing shareholder value is important to everyone— not just shareholders. Lenders, investors, employees, customers all like to work with/invest in companies with high shareholder value, as these companies are better positioned to survive through hard times, keep employees employed, pay back their loans, and offer more pricing flexibility. Total shareholder return (TSR), the stock price appreciation plus reinvested dividends over a period, is one way of looking at shareholder value, and is sometimes considered the ultimate measure of a company’s achievement for shareholders over the long term. The formula for calculating TSR is { (current price – purchase price) + dividends } ÷ purchase price. Higher TSR results in greater capital gains for shareholders, stock price appreciation for employee-owners and potential for future success.
Long-term Investor Value Appropriation (LIVA)
A newer alternative metric is Long-term Investor Value Appropriation (LIVA). The idea behind LIVA is simple is to use historical data to estimate how much value a company either created or destroyed for its entire investor base. This measure is closely related to net present value (NPV), which estimates the value of a project based on expected future cash flow. NPV, which we will cover in the next post, is the gold standard for CFOs to decide which projects to invest in.
After the last several posts, hopefully you have a better understanding of how to understand financial ratios from management and investors perspectives (and how those perspectives come together in an earnings call).
In our next post we will talk about ways to understand ‘return on investment.’ In my mind, this is one of the most critical pieces of financial intelligence a scientific leader can acquire, as they will help you translate the value of the projects you want to advance into a framework your finance partners can more easily understand. So join the mailing list and stay tuned!