
Leadership in Biotech

Tag: cash flow statement

Illustration of a scientist looking at three pipes with money pouring out of them at different rates, representing different aspects of a cash flow statement

The Anatomy of a Cash Flow Statement: Operating, Investing, and Financing

Recall from last time the cash flow statement from BioTechne, and the three main sections.

  1. The first part describes cash flow from operating activities.
  2. The second part is cash flow from investing activities.
  3. The third part is cash flow from financing activities.

Screenshot of the BioTechne Cash Flow Statement

Let’s take these sections one by one.

Operating Activities

As is typical, the first part of the BioTechne cash flow statement describes cash flow from operating activities.

This is the cash the business collected from customers, minus all the cash that was left as any part of the process of producing goods or delivering services for customers. Many consider this category to be the single most important number for understanding the health of the business, because it signals how well the company is doing at turning profits into cash.

In our current economy, many biotech companies are dreaming about having a healthy operating cash flow. This is because a healthy operating cash flow means that further company growth can be internally funded, instead of needing to borrow or sell stock. And when interest rates are high and stock prices are low, external funding options are not particularly attractive.

Investing Activities

The second part is cash flow from investing activities.

Here we find available-for-sale investments, additions to property and equipment, and acquisitions. This section tells us something about how much cash the company is spending on investing for the future. If this number is low relative to the size of the company, then management may be treating the company as a ‘cash cow’ or potentially positioning itself for an acquisition. If the number is high, the company likely has high hopes for the future.

Let’s briefly compare BioTechne to Beckton Dickenson and Illumina on this front by making up a ratio so we can normalize by company size: cash flow from investing (amount spent in investing, so this is actually a negative number)/net income. For BioTechne in 2023, this ratio is 260,893,000/ 835,382,000 = 0.31, this is considerably higher relative to the previous year: 78,281,000/817,371,000 = 0.096. For BD, we get 3,220,000,000/18,870,000,000 = 0.17. For Illumina, 591,000,000/4,584,000,000 = 0.12. In the case of BioTechne in 2023, we see a big investment in Wilson Wolf, a manufacturing firm that invents, designs, and manufactures innovative cell culture devices and associated ancillary products, which accounted for almost 90% of the total investments.
Financing Activities

The third part is cash flow from financing activities.

This is where we find the cash transfers involving the owners or creditors of the business. We see debt repayment, new debt, share repurchases or issues, dividend payments, etc., all here. This category is where we can see the extent to which the company is dependent on outside financing. A positive number here indicates that cash has come into the company through financing activities. A negative figure here indicates when the company has paid out capital, such as retiring or paying off long-term debt or making a dividend payment to shareholders.

For BioTechne, comparing the last couple years is pretty interesting: in 2022 BioTechne used $177,125,000 in financing activities (repurchasing common stock and paying off long-term debt), whereas in 2023, 46,838,000 was provided by financing activities (cash coming into the business, primarily through a line of credit agreement worth 619,661,000, while also paying off long-term debt).

I was a little curious about this part, so I dug around in the footnotes and found this statement:

“In October 2018, the Company entered into forward starting swaps designated as cash flow hedges on outstanding debt. The forward starting swaps reduce the variability of cash flow payments for the Company by converting the variable interest rate on the Company’s long-term debt described in Note 6 to that of a fixed interest rate. … In May 2021, the Company entered into a new forward starting swap designated as a cash flow hedge on forecasted debt. The forward starting swap reduces the variability of cash flow payments for the Company by converting the variable interest rate on the Company’s forecasted variable interest long-term debt to that of a fixed interest rate.”

Aren’t footnotes fun? 😉

Summary Section

After the cash flow from financing activities, you can see a summary section:
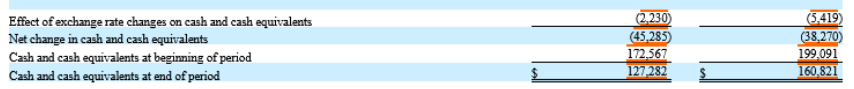
Screenshot of a summary from the BioTechne Cash Flow Statement

One interesting thing to notice here is the first line, ‘Effect of exchange rate changes on cash and cash equivalents.’ If you recall from our very first substantive post on finding financial statements using EDGAR and its utility in learning a new-to-you business, BioTechne listed international exchange rates (the price of one currency expressed in terms of another currency) as one of their financial risks, as is fairly typical in the Life Sciences. Let’s dig into this topic a bit further here.

Whenever a company from one country does business in another, the financial health of its operations will be affected by changes in exchange rates. Let’s say you buy 96-well plates from China, at a price of $0.50 USD per plate, and you are buying ~200,000/month, for a total of $100K transacted per month. With an exchange rate of ~$1 USD for 7 Chinese Yuan, you are paying 700K Yuan for these plates, or 3.5 Yuan per plate. Now let’s imagine the exchange rate changes to $1 USD = 7.5 Chinese Yuan. Each plate still costs 3.5 Yuan, but you now need only $0.47 USD for each plate, meaning your monthly order just got cheaper by ~$7K USD. The opposite situation, where the Yuan becomes stronger against the dollar as it did in the beginning of 2022, will lead to your monthly order costs effectively going up. This example is pretty simplistic, but hopefully it provides a sense of why exchange rates are important for companies with global supply chains.

And that concludes our consideration of the cash flow statement, and wraps up our dive into the three main financial statements (income statement, balance sheet, and cash flow statement).

In the next post, we’ll move on to touch on key financial ratios and why they are important. It’s not too late to join the mailing list to receive an update when it’s published!

Navigating a company’s financial condition with the cash flow statement

“Cash is king,” or so they say. Let’s see how this plays out in the Cash Flow Statement.

We’ve already covered two of the three foundational financial statements— the balance sheet and the income statement.

The balance sheet told us about what the business owns, and what it owes. We use that information to understand the potential to create value for customers.

The income statement told us about the profitability of the business, or how much it costs to generate each dollar of revenue.

Let’s now turn to the third and final foundational financial statement.

The Cash Flow Statement

The cash flow statement is a recording of all the cash that entered and left the business over a period of time. It’s also the financial statement least subject to biases that creep in due to assumptions and estimates. The famous investor Warren Buffet is known to put the greatest emphasis on the cash flow statement when he examines financial statements, paying particular attention to ‘owner earnings.’  The owner earnings (also known as “Free Cash Flow”) can be calculated directly from the cash flow statement by finding the difference between the operating activities and the capital expenditures (i.e., the cash flow from investing activities).

The cash flow statement can provide insight into the financial health and status of an organization.

Specifically, by looking at the cash flow statement, we can answer the following kinds of questions:

  • What is the liquidity situation of the company (i.e., what can be readily converted to cash)?
  • What are the company’s sources of cash?
  • Is there free cash flow being generated to further invest in assets or operations?
  • Is the overall cash increasing or decreasing? How stable is it across different time frames?

The cash flow statement has an important structure. Below is the cash flow statement for BioTechne:

Screenshot of the BioTechne Cash Flow Statement

You can see in this example that there are three sections.

  1. The first part describes cash flow from operating activities— cash flow that’s generated once the company delivers its regular goods or services
  2. The second part is cash flow from investing activities— cash flow from purchasing or selling assets (both physical and non-physical property) using cash, not debt (sometimes referred to as capital expenditures)
  3. The third part is cash flow from financing activities— cash flow from both debt and equity financing

Finally, there is a summary section at the bottom that looks like this:

Screenshot of a summary from the BioTechne Cash Flow Statement

This section tells us whether BioTechne is cash flow positive or negative in the ‘Net change in cash and cash equivalents’ line. So in both 2022 and 2023, BioTechne was cash flow negative, meaning the cash outflow was higher than the cash inflow during that period.

Cash flow vs. profit

Negative cash flow doesn’t necessarily mean profit is lost. Instead, negative cash flow may be caused by a company’s decision to expand the business and invest in future growth. It can also indicate an expenditure and income mismatch, which should be addressed as soon as possible.  Similarly, positive cash flow, while ideal, does not necessarily translate to profit. A business can be profitable without being cash flow-positive, and can have positive cash flow without actually making a profit (often through borrowing money).

Here it’s important to remember that profit is typically defined as the balance that remains when all of a business’s operating expenses are subtracted from its revenues, it answers the question: how much money is left over from selling a product after all expenses from producing it have been paid? This is fundamentally a different question than what cash flow answers, which centers more around whether a company has enough liquidity or cash to pay its expenses.

In a nutshell, this is why it’s important to look at financial statements together.

We’ll dig in more to the three sections of the cash flow statement in our next post. Stay tuned with via the mailing list for updates!

Stylized illustration of a scientist examining an income statement, a balance sheet, and a cash flow statement

Every scientist’s dream: Understanding financial statements

Every company that trades on the stock market has to share their financial results every three months, i.e., quarterly. Once a year, they produce an annual report, which is basically a blown out version of these quarterly documents.. You know those “10-K (annual reports) and 10-Q (quarterly reports)” we found for Bio-Techne on EDGAR? That’s what I’m talking about. 🙂

There’s quite a bit you can learn from these documents, but here we will focus on the financial statements.

The main statements are

  • the income statement,
  • the balance sheet, and
  • the cash flow statement.

These statements are not just for life sciences companies. All companies that trade on the stock market are required to file these documents. Nonprofit organizations and government agencies use similar statements, although there are a few key differences we won’t cover here.

The income statement shows us how much money the company makes. This statement matches the expenses with the revenue, so one can see how efficient the company is at making money.

The balance sheet shows us what the company has (i.e. its assets) and what it owes (i.e. its liabilities). The difference between assets and liabilities is equity, the part that belongs to the owners/shareholders of the company.

The cash flow statement simply tracks how much money is coming in and going out of the business over a period of time. As soon as money moves in or out, the cash flow result is recorded.

Putting together the full picture

These three statements together give us a clear picture of how well the company is doing financially. Of course, there’s considerable nuance in how a company approaches these statements that can impact how well or poorly it looks like it’s doing. There are rules governing accounting and finance, but there’s also quite a bit of art to it, and when companies get too creative or allow significant bias to creep in based on market pressure, that’s where you start to head towards fraud and financial ruin. We’ll cover that along the way, too.

One way to think about accounting is similar to the way you would run a scientific experiment – In an experiment you have controls – to measure the result vs a comparison point.  One of the most fundamental accounting rules for GAAP (Generally Accepted Accounting Principles) is that GAAP is consistently applied- so you have a control in place and can do valid comparisons between quarters, years and months, just like a good trial or experiment.

These financial statements are the gold mine of information that stock analysts use to figure out how much these companies are worth, and what their stock price should be.

While stock analysts also look at other data outside of these basic financial statements, even if you only had the data in these statements, you’d have a strong understanding of the company’s past performance and current state. And from there, with some insight into the market that the company operates in, you can start to make some predictions about the future.

In the next part, we’ll explore the income statement. We’ll go through the structure of it, then we’ll look at some real world examples.

Stay tuned! (Which is easier if you join my mailing list to be updated when the next installment comes out.)

Powered by WordPress & Theme by Anders Norén