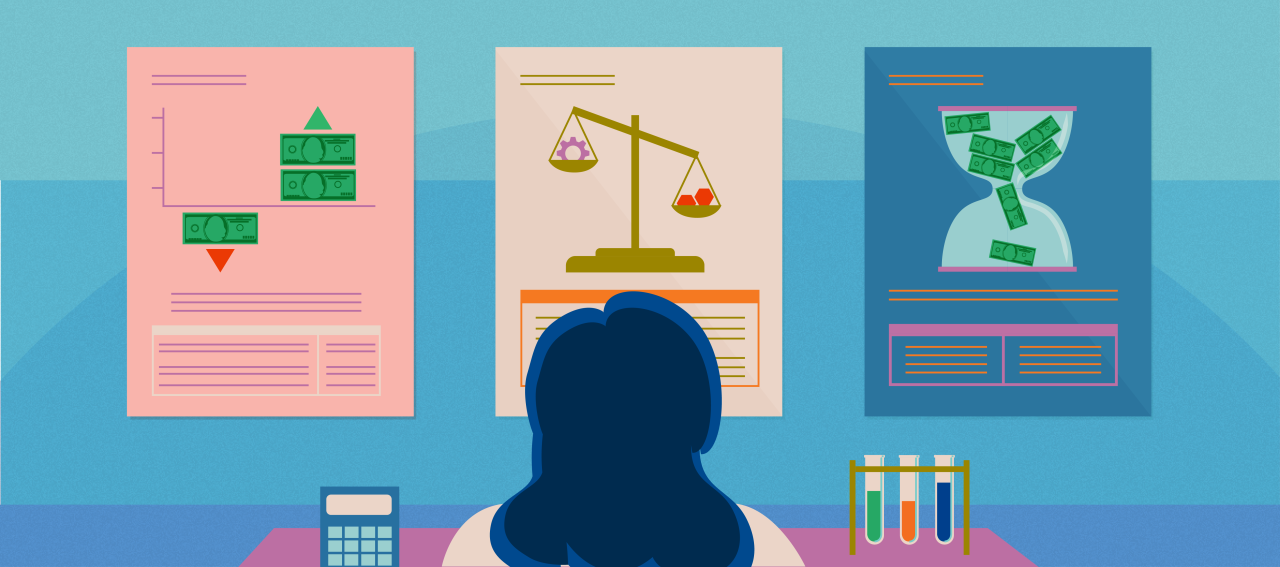
Every company that trades on the stock market has to share their financial results every three months, i.e., quarterly. Once a year, they produce an annual report, which is basically a blown out version of these quarterly documents.. You know those “10-K (annual reports) and 10-Q (quarterly reports)” we found for Bio-Techne on EDGAR? That’s what I’m talking about. 🙂
There’s quite a bit you can learn from these documents, but here we will focus on the financial statements.
The main statements are
- the income statement,
- the balance sheet, and
- the cash flow statement.
These statements are not just for life sciences companies. All companies that trade on the stock market are required to file these documents. Nonprofit organizations and government agencies use similar statements, although there are a few key differences we won’t cover here.
The income statement shows us how much money the company makes. This statement matches the expenses with the revenue, so one can see how efficient the company is at making money.
The balance sheet shows us what the company has (i.e. its assets) and what it owes (i.e. its liabilities). The difference between assets and liabilities is equity, the part that belongs to the owners/shareholders of the company.
The cash flow statement simply tracks how much money is coming in and going out of the business over a period of time. As soon as money moves in or out, the cash flow result is recorded.
More in this series
- Why am I writing about finance?
- How to learn the financial basics about a new (to you) business
- Every scientist’s dream: Understanding financial statements
- A first look at income statements: revenue, costs and profits
- What scientists need to understand about revenue and its recognition
- Income Statement Fun: What is included in the Cost of Sales and why you should care
- How expenses and depreciation can affect the profitability of your scientific work
- Profitability: the proverbial and literal bottom line
- Using the Balance Sheet to Understand a Company’s Financial Health
- Assets: tangible, intangible, and goodwill
- Decoding Financial Health with Liabilities & Equity from the Balance Sheet
- Navigating a company’s financial condition with the cash flow statement
- The Anatomy of a Cash Flow Statement: Operating, Investing, and Financing
- Budgeting 101: Using our newly acquired financial intelligence to make sense of the budgeting process
- Making Sense of the Numbers Through Financial Ratios
- Your Company’s Quarterly Earnings Call: How to Make Sense of It All
- The “Big Five” Numbers — What Investors Care About and Why
- Net Present Value: Making the Financial Case for Advancing Scientific Projects You Care About
Putting together the full picture
These three statements together give us a clear picture of how well the company is doing financially. Of course, there’s considerable nuance in how a company approaches these statements that can impact how well or poorly it looks like it’s doing. There are rules governing accounting and finance, but there’s also quite a bit of art to it, and when companies get too creative or allow significant bias to creep in based on market pressure, that’s where you start to head towards fraud and financial ruin. We’ll cover that along the way, too.
One way to think about accounting is similar to the way you would run a scientific experiment – In an experiment you have controls – to measure the result vs a comparison point. One of the most fundamental accounting rules for GAAP (Generally Accepted Accounting Principles) is that GAAP is consistently applied- so you have a control in place and can do valid comparisons between quarters, years and months, just like a good trial or experiment.
These financial statements are the gold mine of information that stock analysts use to figure out how much these companies are worth, and what their stock price should be.
While stock analysts also look at other data outside of these basic financial statements, even if you only had the data in these statements, you’d have a strong understanding of the company’s past performance and current state. And from there, with some insight into the market that the company operates in, you can start to make some predictions about the future.
In the next part, we’ll explore the income statement. We’ll go through the structure of it, then we’ll look at some real world examples.
Stay tuned! (Which is easier if you join my mailing list to be updated when the next installment comes out.)
Comments
Powered by WP LinkPress