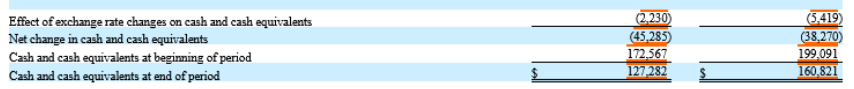
Leadership in Biotech

Tag: financial statements

Illustration of a scientist working at a chalkboard covered in pictures representing financial ratios

Making Sense of the Numbers Through Financial Ratios

In this post we will move beyond the financial statements and consider briefly a few key financial ratios and why they are important. 

In previous posts, we’ve sometimes evoked ratios to try to contextualize and compare various numbers in the financial statements. And in general, this is exactly what ratios are good for. In this post, we’ll cover four different categories of financial ratios: 

  • Profitability, 
  • Leverage, 
  • Liquidity, and 
  • Efficiency.

Profitability Ratios

Simply put, these ratios evaluate a company’s ability to generate profits. There are dozens of profitability ratios, so below I highlight some of the most important ones. 

  • Gross Profit Margin
    • What it is: Gross Profit Margin (sometimes called simply gross margin) = gross profit/revenue
    • Why it matters: Gross margin shows the basic profitability of the product and/or service itself, before expenses or overhead. In other words, how much of the sale price is going to the materials and direct labor to produce that product or service. 
    • What to pay attention to: 
      • Higher is generally better- if you can’t cover your direct costs by selling your goods, you won’t be in business long.
      • Trend lines are important- negative trend can mean that the company may be discounting sales to increase volume or CoGs is increasing (or both). A negative trend can be an early warning indicator that a business may be in trouble.
  • Operating Profit Margin
    • What it is: Operating Profit Margin (Operating Margin) = operating profit (EBIT)/revenue
    • Why it matters: Operating margin is a more comprehensive measure of a company’s ability to generate a profit, as it uses operating profit, or EBIT (earnings before interest and taxes), as a numerator.  Here you are looking at how well the company is running itself.
    • What to pay attention to: a downward trend is a signal for management (and investors) to pay attention- costs are rising faster than sales.
  • Net Profit Margin
    • What it is: Net Profit Margin (Net Margin) = net profit/revenue
    • Why it matters: This ratio indicates how much of every sales dollar a company gets to keep after everything else has been paid for. Net profit is that proverbial bottom line, to this is the bottom line ratio. People sometimes refer to this as return on sales, or ROS.
    • What to pay attention to: This ratio is highly variable from industry to industry, so it is usually most meaningful to compare a company’s net margin across time and/or compare with players in the same industry. 
  • Return on Assets
    • What it is: Return on Assets (ROA) = net profit/total assets
    • Why it matters: ROA tells you what percentage of every dollar invested in the business was returned as profit. Stated otherwise, this ratio looks at how well a company is putting its assets (cash, facilities, inventory, etc) to work.
    • What to pay attention to: Unlike the other Profitability Ratios we’ve discussed so far, ROA can be too high. An ROA above the industry norm can indicate that a company is not investing in its asset base for the future, which can compromise long term prospects. ROA varies from industry to industry, so like with the other metrics, it’s best to compare amongst peers within an industry. There are more nefarious reasons ROA can be inflated (remember Enron?), but we’ll set those aside for now. 
  • Return of Equity
    • What it is: Return on Equity (ROE) = net profit/shareholders’ equity
    • Why it matters: While assets refer to what the company owns, equity refers to its net worth as determined by accounting rules. So ROE indicates the profit made for every dollar of equity invested in the company. 
    • What to pay attention to: From an investor’s perspective, s/he’ll generally be looking for a ROE above the going interest rates and asking the basic question: is this company even capable of generating a return that is worth the risk of investment? From a financial health perspective, this ratio is a bit tricky vis-a-vis comparison to other companies. A company’s ROE can be higher than a competitor because it has borrowed more money. Whether this position is good or bad will heavily depend on how smart the company has been in borrowing money. 
  • Other/Variations on a theme
    • Return on net assets (RONA), Return on total capital (ROTC), return on invested capital (ROIC), and return on capital employed (ROCE) are some other profitability ratios. They all answer the same basic question: did the company earn enough profit to justify the amount of ‘other people’s money’ it is using?
    • Generic formula: (net income before interest on debt and after tax)/(total equity + total interest bearing debt)
    • For the sake of brevity, we will not go into more depth here.

Leverage Ratios

These ratios evaluate how (and how extensively) a company uses debt. Fun fact: a financial analyst’s word for debt is leverage. So now you know. Leverage allows companies to make more money, but it also increases risk, because it introduces fixed costs that cannot easily be cut in the case of revenue reduction. 

  • Debt-to-Equity
    • What it is: Debt-to-Equity Ratio = Total Liabilities/Shareholders’ Equity
    • Why it matters: This ratio is often used by bankers to determine whether or not to offer a company a loan. 
    • What to pay attention to: Managers should care about this ratio, as raising cash through borrowing may be more difficult if this ratio is high, and expansion could require more equity investment. 
  • Interest Coverage
    • What it is: Interest Coverage = operating profit/annual interest charges
    • Why it matters: The ratio shows how easy it will be for a company to pay its interest. Bankers love it.
    • What to pay attention to: High ratio indicates that a company can reasonably take on more debt. If this ratio is close to 1, it indicates that most of the operative profit is used to pay interest- not good. In that situation, senior management will need to focus on paying off debt. 
    • Side note: there’s a sneaky construct called an operating lease, where companies lease equipment from an investor instead of buying it- then these lease payments show up as an expense on the income statement, but there is no asset and so no asset-related debt. 

Liquidity Ratios

Simply put, these ratios evaluate how well a company is able to pay its bills.

  • Current Ratio
    • What it is: Current ratio = current assets/current liabilities
    • Why it matters: It provides a measure of the company’s cash runway.
    • What to pay attention to: Too high or too low is a problem. Too high suggests the company is sitting on cash instead of investing it or returning it to shareholders. Too low (close to 1) means that the company is just barely able to cover its liabilities with the cash coming in. If this ratio is less than 1, then the company is going to run out of cash in the coming year and needs to generate more cash or attract more from investors.
  • Quick Ratio
    • What it is: Quick ratio = (current assets – inventory)/current liabilities
    • Why it matters: Also known as the ‘acid test,’ this ratio is a variation on the Current Ratio, but subtracting inventory, which is harder to convert to cash quickly. In other words, this ratio indicates a company’s ability to pay off short-term debt without needing to wait for inventory to sell.
    • What to pay attention to: If a particular business has a lot of their assets tied up in inventory (for instance, a reagent or consumable manufacturer), then lenders and vendors will be looking to see that this ratio is well about 1.
Efficiency Ratios

These ratios evaluate how efficiently a company is managing its assets (and liabilities), which can have a direct impact on the company’s cash position.

  • Inventory Days 
    • What it is: Days in Inventory (DII) = average inventory/(COGS/Day)
    • Why it matters: This ratio measures the number of days inventory stays in the system. Inventory is somewhat ‘frozen cash,’ so the faster you turn it over, the better off you will be. It is used as a benchmark of operational efficiency.
    • What to pay attention to: What good looks like for this ratio will depend heavily on the industry, so best to benchmark to other players in your space.
  • Inventory Turnover
    • What it is: Inventory turns = 360/DII
    • Why it matters: If every item of inventory was processed at exactly the same rate, inventory turns would be the number of times per year you sold our your stock and had to replenish it. 
    • What to pay attention to: The higher the number of inventory turns, the tighter your management of inventory and the better your cash position. All else being equal, you want to increase this value. 
  • Days Sales Outstanding
    • What it is: DSO = ending accounts receivable/ (revenue/day)
    • Why it matters: This ratio is a measure of the time it takes to collect the cash from sales- how fast to customers pay their bills. Note that in the diagnostics space, this ratio may be high, as your payors are insurance companies, hospital systems, or the government, who aren’t necessarily known for their speediness.
    • What to pay attention to: Lower DSO means a stronger cash position. A high DSO can be a red flag, but it is important to contextualize this value based on the industry you are in.
  • Days Payable Outstanding
    • What it is: DPO = ending accounts payable/(COGS/day)
    • Why it matters: This ratio measures how long it takes a company to pay its own invoices. It’s the flipside of DSO.
    • What to pay attention to: A higher DPO means a stronger cash position, as you are holding onto your money for longer. However, this may not make your vendors very happy, so a balance must be struck. There are companies who have mastered the art of collecting payment from sales quickly, but paying vendors slowly, such that they have a very strong cash position. 
  • Property, Plant, and Equipment Turnover
    • What it is: PPE turnover = revenue/PPE
    • Why it matters: PPE turnover is a measure of how efficient a company is at generating revenue from fixed assets such as buildings and equipment. 
    • What to pay attention to: All other things being equal, the higher this ratio, the better the company is at putting its assets to work. However, companies may lease instead of buy equipment, which can make it challenging to compare across companies, as operating leases may not show up on the balance sheet (operating leases show up as an expense on the income statement).
  • Total Asset Turnover
    • What it is: Total asset turnover = revenue/total assets
    • Why it matters: Similar to PPE turnover, but looks at total assets, not just fixed assets. It measures the efficiency in the use of all assets.
    • What to pay attention to: This metric measures efficiency- tracking the trends here can help you measure your overall efficiency in using your assets.

In the next post, we will look at what ratios investors care about: the “Big Five” numbers. Please consider subscribing to be notified when it’s out!
Illustration of a scientist looking at three pipes with money pouring out of them at different rates, representing different aspects of a cash flow statement

The Anatomy of a Cash Flow Statement: Operating, Investing, and Financing

Recall from last time the cash flow statement from BioTechne, and the three main sections.

  1. The first part describes cash flow from operating activities.
  2. The second part is cash flow from investing activities.
  3. The third part is cash flow from financing activities.

Screenshot of the BioTechne Cash Flow Statement

Let’s take these sections one by one.

Operating Activities

As is typical, the first part of the BioTechne cash flow statement describes cash flow from operating activities.

This is the cash the business collected from customers, minus all the cash that was left as any part of the process of producing goods or delivering services for customers. Many consider this category to be the single most important number for understanding the health of the business, because it signals how well the company is doing at turning profits into cash.

In our current economy, many biotech companies are dreaming about having a healthy operating cash flow. This is because a healthy operating cash flow means that further company growth can be internally funded, instead of needing to borrow or sell stock. And when interest rates are high and stock prices are low, external funding options are not particularly attractive.

Investing Activities

The second part is cash flow from investing activities.

Here we find available-for-sale investments, additions to property and equipment, and acquisitions. This section tells us something about how much cash the company is spending on investing for the future. If this number is low relative to the size of the company, then management may be treating the company as a ‘cash cow’ or potentially positioning itself for an acquisition. If the number is high, the company likely has high hopes for the future.

Let’s briefly compare BioTechne to Beckton Dickenson and Illumina on this front by making up a ratio so we can normalize by company size: cash flow from investing (amount spent in investing, so this is actually a negative number)/net income. For BioTechne in 2023, this ratio is 260,893,000/ 835,382,000 = 0.31, this is considerably higher relative to the previous year: 78,281,000/817,371,000 = 0.096. For BD, we get 3,220,000,000/18,870,000,000 = 0.17. For Illumina, 591,000,000/4,584,000,000 = 0.12. In the case of BioTechne in 2023, we see a big investment in Wilson Wolf, a manufacturing firm that invents, designs, and manufactures innovative cell culture devices and associated ancillary products, which accounted for almost 90% of the total investments.

Financing Activities

The third part is cash flow from financing activities.

This is where we find the cash transfers involving the owners or creditors of the business. We see debt repayment, new debt, share repurchases or issues, dividend payments, etc., all here. This category is where we can see the extent to which the company is dependent on outside financing. A positive number here indicates that cash has come into the company through financing activities. A negative figure here indicates when the company has paid out capital, such as retiring or paying off long-term debt or making a dividend payment to shareholders.

For BioTechne, comparing the last couple years is pretty interesting: in 2022 BioTechne used $177,125,000 in financing activities (repurchasing common stock and paying off long-term debt), whereas in 2023, 46,838,000 was provided by financing activities (cash coming into the business, primarily through a line of credit agreement worth 619,661,000, while also paying off long-term debt).

I was a little curious about this part, so I dug around in the footnotes and found this statement:

“In October 2018, the Company entered into forward starting swaps designated as cash flow hedges on outstanding debt. The forward starting swaps reduce the variability of cash flow payments for the Company by converting the variable interest rate on the Company’s long-term debt described in Note 6 to that of a fixed interest rate. … In May 2021, the Company entered into a new forward starting swap designated as a cash flow hedge on forecasted debt. The forward starting swap reduces the variability of cash flow payments for the Company by converting the variable interest rate on the Company’s forecasted variable interest long-term debt to that of a fixed interest rate.”

Aren’t footnotes fun? 😉

Summary Section

After the cash flow from financing activities, you can see a summary section:

Screenshot of a summary from the BioTechne Cash Flow Statement

One interesting thing to notice here is the first line, ‘Effect of exchange rate changes on cash and cash equivalents.’ If you recall from our very first substantive post on finding financial statements using EDGAR and its utility in learning a new-to-you business, BioTechne listed international exchange rates (the price of one currency expressed in terms of another currency) as one of their financial risks, as is fairly typical in the Life Sciences. Let’s dig into this topic a bit further here.

Whenever a company from one country does business in another, the financial health of its operations will be affected by changes in exchange rates. Let’s say you buy 96-well plates from China, at a price of $0.50 USD per plate, and you are buying ~200,000/month, for a total of $100K transacted per month. With an exchange rate of ~$1 USD for 7 Chinese Yuan, you are paying 700K Yuan for these plates, or 3.5 Yuan per plate. Now let’s imagine the exchange rate changes to $1 USD = 7.5 Chinese Yuan. Each plate still costs 3.5 Yuan, but you now need only $0.47 USD for each plate, meaning your monthly order just got cheaper by ~$7K USD. The opposite situation, where the Yuan becomes stronger against the dollar as it did in the beginning of 2022, will lead to your monthly order costs effectively going up. This example is pretty simplistic, but hopefully it provides a sense of why exchange rates are important for companies with global supply chains.

And that concludes our consideration of the cash flow statement, and wraps up our dive into the three main financial statements (income statement, balance sheet, and cash flow statement).

In the next post, we’ll move on to touch on key financial ratios and why they are important. It’s not too late to join the mailing list to receive an update when it’s published!

Navigating a company’s financial condition with the cash flow statement

“Cash is king,” or so they say. Let’s see how this plays out in the Cash Flow Statement.

We’ve already covered two of the three foundational financial statements— the balance sheet and the income statement.

The balance sheet told us about what the business owns, and what it owes. We use that information to understand the potential to create value for customers.

The income statement told us about the profitability of the business, or how much it costs to generate each dollar of revenue.

Let’s now turn to the third and final foundational financial statement.

The Cash Flow Statement

The cash flow statement is a recording of all the cash that entered and left the business over a period of time. It’s also the financial statement least subject to biases that creep in due to assumptions and estimates. The famous investor Warren Buffet is known to put the greatest emphasis on the cash flow statement when he examines financial statements, paying particular attention to ‘owner earnings.’  The owner earnings (also known as “Free Cash Flow”) can be calculated directly from the cash flow statement by finding the difference between the operating activities and the capital expenditures (i.e., the cash flow from investing activities).

The cash flow statement can provide insight into the financial health and status of an organization.

Specifically, by looking at the cash flow statement, we can answer the following kinds of questions:

  • What is the liquidity situation of the company (i.e., what can be readily converted to cash)?
  • What are the company’s sources of cash?
  • Is there free cash flow being generated to further invest in assets or operations?
  • Is the overall cash increasing or decreasing? How stable is it across different time frames?

The cash flow statement has an important structure. Below is the cash flow statement for BioTechne:

Screenshot of the BioTechne Cash Flow Statement

You can see in this example that there are three sections.

  1. The first part describes cash flow from operating activities— cash flow that’s generated once the company delivers its regular goods or services
  2. The second part is cash flow from investing activities— cash flow from purchasing or selling assets (both physical and non-physical property) using cash, not debt (sometimes referred to as capital expenditures)
  3. The third part is cash flow from financing activities— cash flow from both debt and equity financing

Finally, there is a summary section at the bottom that looks like this:

Screenshot of a summary from the BioTechne Cash Flow Statement

This section tells us whether BioTechne is cash flow positive or negative in the ‘Net change in cash and cash equivalents’ line. So in both 2022 and 2023, BioTechne was cash flow negative, meaning the cash outflow was higher than the cash inflow during that period.

Cash flow vs. profit

Negative cash flow doesn’t necessarily mean profit is lost. Instead, negative cash flow may be caused by a company’s decision to expand the business and invest in future growth. It can also indicate an expenditure and income mismatch, which should be addressed as soon as possible.  Similarly, positive cash flow, while ideal, does not necessarily translate to profit. A business can be profitable without being cash flow-positive, and can have positive cash flow without actually making a profit (often through borrowing money).

Here it’s important to remember that profit is typically defined as the balance that remains when all of a business’s operating expenses are subtracted from its revenues, it answers the question: how much money is left over from selling a product after all expenses from producing it have been paid? This is fundamentally a different question than what cash flow answers, which centers more around whether a company has enough liquidity or cash to pay its expenses.

In a nutshell, this is why it’s important to look at financial statements together.

We’ll dig in more to the three sections of the cash flow statement in our next post. Stay tuned with via the mailing list for updates!

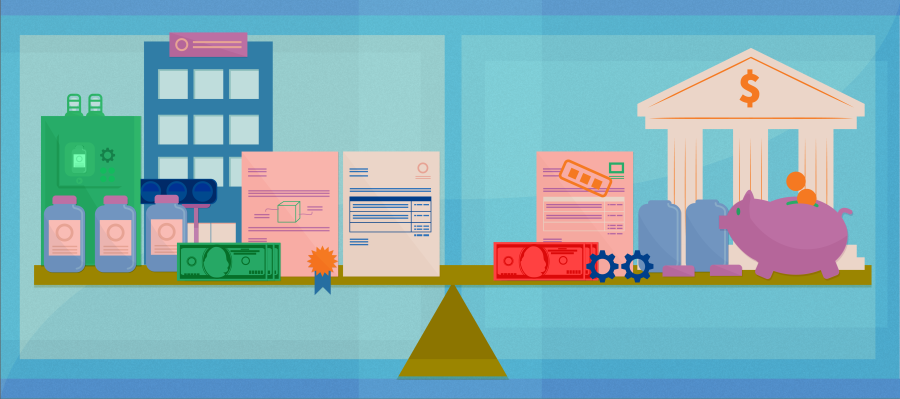
Illustration of various elements of a balance sheet, such as patents, cash and due invoices, sitting in balance on a seesaw

Using the Balance Sheet to Understand a Company’s Financial Health

To review, the big three in terms of financial statements are:

  • the income statement,
  • the balance sheet, and
  • the cash flow statement.

In this post, we will talk about the importance of a balance sheet.

Remember that a balance sheet tells us what a company owns, i.e. its assets, versus what it owes, i.e. its liabilities.

Equity measures the extent to which assets exceed liabilities, and is what “belongs” to the owners of the company.

Assets and liabilities are connected with equity via the fundamental equation of accounting:

Assets – Liabilities = Equity

Why do we care about balance sheets?

First, healthy companies have more assets than liabilities. And looking at how assets, liabilities, and equity have trended over time helps us understand whether a company is getting healthier or sicker.

Profitability (discussed in the income statement section) relates to equity, in the same way a grade in college relates to your overall GPA. You can think of profitability sort of like a single course grade, whereas equity is more like your grade point average. A single course grade will influence your GPA, but it doesn’t define it. Similarly, a strong quarter of profits will increase the equity in your balance sheet, and vice versa. Over time, the equity reflects the accumulation of profits and losses.

Second, balance sheets tell us about leverage (here’s a fun vocabulary lesson for you: a financial analyst’s word for debt is leverage). How much debt does the company rely on?

The higher the debt load, the higher the company’s debt service costs, which reduces its ability to invest or spend in other ways.

Balance sheet takeaways

These are the kinds of questions about a company’s financial health that you can answer with the balance sheet:

  • How much debt does the company have relative to equity?
  • How liquid is the business in the short term (less than one year)- can it pay its bills?
  • What percentage of assets are tangible and what percentage comes from financial transactions?
  • Is the financial health of the company moving in the right direction- is the equity increasing over time?

Short post for today, but next time we’ll dig into the first part of the balance sheet: Assets, including a particularly interesting asset category called ‘Goodwill.’

A first look at income statements: revenue, costs and profits

Today we talk about the income statement, possibly the most discussed financial statement.

The income statement attempts to measure whether the products or services that a company provides are profitable when everything gets added up. In other words, how many sales did a company make during a period of time, how much did it cost to make those sales, and what profit is left over.

The income statement can help answer the following questions about a company’s financial health:

  • How much is revenue growing?
  • What is the gross profit margin for sales?
  • What percentage of revenue results in net profit after all expenses?
  • How much does the business repay shareholders versus reinvesting (and what that might mean for how the company sees its future)?

As a quick aside, there’s a fundamental accounting rule called ‘The Matching Principle’ at play in the income statement that is worth mentioning here. Briefly, the matching principle seeks to match the cost with its associated revenue to determine profits in a given time period. This principle will come up throughout the sections about the income statement.

There are always 3 main categories on an income statements:

  • Sales or revenue is at the top (fun fact: when fancy people say ‘top-line growth’ they mean sales growth, because sales is always at the top of the income statement)
  • Costs and expenses are in the middle
  • Profit is at the bottom

Today, we will focus on just identifying how to read these statements.

Parsing the Income Statement

To do that, let’s go back to Bio-Techne and take a look at their annual income statement for 2022 by pulling up the most recent 10-K filing again.

First thing to notice is that it doesn’t say ‘Income Statement.’ Instead, it has this:

Report text: Item 8. Financial Statements and Supplementary Data. Consolidated Statements of Earnings and Comprehensive Income

It can also be called the ‘profit and loss statement’ or ‘P&L statement’ or ‘operating statement’ or ‘statement of operations’ or ‘statement of earnings’ or ‘earnings statement’ or some combination therein, like we have here for our example. Sometimes it feels like those crafty finance people intentionally obfuscate things. 😉

The other things to notice here are that

  • we are looking at the income statement for the Bio-Techne Corporation and Subsidiaries, i.e., the whole company, not one division, and
  • numbers are listed in thousands- sometimes this can be millions, so best to pay attention.

So here it is for Bio-Techne. The Income Statement. Remember, sales or revenue is at the top, costs and expenses are in the middle, profit is at the bottom. We’ll take these each separately in the upcoming posts.

Screenshot of Bio-Techne Income Statement

A note on footnotes

Before we wrap up today, I want to draw your attention to the ‘See Notes to Consolidated Financial Statements’ at the bottom of the Income Statement.

These footnotes are required per the rules of accounting to explain how the totals were arrived at. Remember that the rules of accounting are meant to be applied consistently, so that one can readily compare trends over time. However, it can be perfectly legitimate to modify the approach, and that modification will be called out in the footnotes. So, every now and again there are very interesting nuggets in the footnotes, however, there are usually quite a lot of them.

Here’s an example footnote about inventory basically explaining that they make more than the sales demand due to ‘economies of scale through a highly controlled manufacturing process.’ Those of you who have worked in regulated manufacturing environments on these types of products will know that manufacturing runs or batch sizes are validated at particular amounts/volumes- you can’t just manufacture to whatever volume you want, and that impacts the financial statements:

Screenshot of a footnote concerning inventories from a Bio-Techne Income Statement

That covers the basics. In the next post, we’ll talk about revenue! As always, you can sign up to the mailing list to be updated when the next installment is out.

Stylized illustration of a scientist examining an income statement, a balance sheet, and a cash flow statement

Every scientist’s dream: Understanding financial statements

Every company that trades on the stock market has to share their financial results every three months, i.e., quarterly. Once a year, they produce an annual report, which is basically a blown out version of these quarterly documents.. You know those “10-K (annual reports) and 10-Q (quarterly reports)” we found for Bio-Techne on EDGAR? That’s what I’m talking about. 🙂

There’s quite a bit you can learn from these documents, but here we will focus on the financial statements.

The main statements are

  • the income statement,
  • the balance sheet, and
  • the cash flow statement.

These statements are not just for life sciences companies. All companies that trade on the stock market are required to file these documents. Nonprofit organizations and government agencies use similar statements, although there are a few key differences we won’t cover here.

The income statement shows us how much money the company makes. This statement matches the expenses with the revenue, so one can see how efficient the company is at making money.

The balance sheet shows us what the company has (i.e. its assets) and what it owes (i.e. its liabilities). The difference between assets and liabilities is equity, the part that belongs to the owners/shareholders of the company.

The cash flow statement simply tracks how much money is coming in and going out of the business over a period of time. As soon as money moves in or out, the cash flow result is recorded.

Putting together the full picture

These three statements together give us a clear picture of how well the company is doing financially. Of course, there’s considerable nuance in how a company approaches these statements that can impact how well or poorly it looks like it’s doing. There are rules governing accounting and finance, but there’s also quite a bit of art to it, and when companies get too creative or allow significant bias to creep in based on market pressure, that’s where you start to head towards fraud and financial ruin. We’ll cover that along the way, too.

One way to think about accounting is similar to the way you would run a scientific experiment – In an experiment you have controls – to measure the result vs a comparison point.  One of the most fundamental accounting rules for GAAP (Generally Accepted Accounting Principles) is that GAAP is consistently applied- so you have a control in place and can do valid comparisons between quarters, years and months, just like a good trial or experiment.

These financial statements are the gold mine of information that stock analysts use to figure out how much these companies are worth, and what their stock price should be.

While stock analysts also look at other data outside of these basic financial statements, even if you only had the data in these statements, you’d have a strong understanding of the company’s past performance and current state. And from there, with some insight into the market that the company operates in, you can start to make some predictions about the future.

In the next part, we’ll explore the income statement. We’ll go through the structure of it, then we’ll look at some real world examples.

Stay tuned! (Which is easier if you join my mailing list to be updated when the next installment comes out.)

Powered by WordPress & Theme by Anders Norén