Today we will talk about revenue.
Revenue seems like a pretty obvious concept: the dollar value of the products and services a company provided to its customers during a given period of time (remember the ‘Matching Principle’ we talked about in the last post?).
There are some subtleties here, because in order to record something as revenue, it must have been ‘earned.’ If you are selling a reagent, then you must have shipped it to your customer. If you are performing a service, say running a diagnostic test, then you should have performed the work. Easy enough? Sure, but consider:
Say BioTechne allows a customer to order reagents ahead of when they will need them (for instance, maybe the customer is looking to control the number of lots they have), but because this is a particularly important, high volume account, BioTechne is willing to hold those particular lots of reagents until the customer needs them (i.e., you haven’t shipped them yet). When can they recognize that revenue?
Or let’s say the diagnostics side of the business, ExosomeDx, signs a multi-year pharma contract for processing and analysis of clinical samples. When do they get to recognize the revenue from that deal? When the samples are run? Or when the complete analysis is delivered to the client?
Let’s keep these points in mind as we look through the numbers.
Below is the screenshot of the income statement for BioTechne:
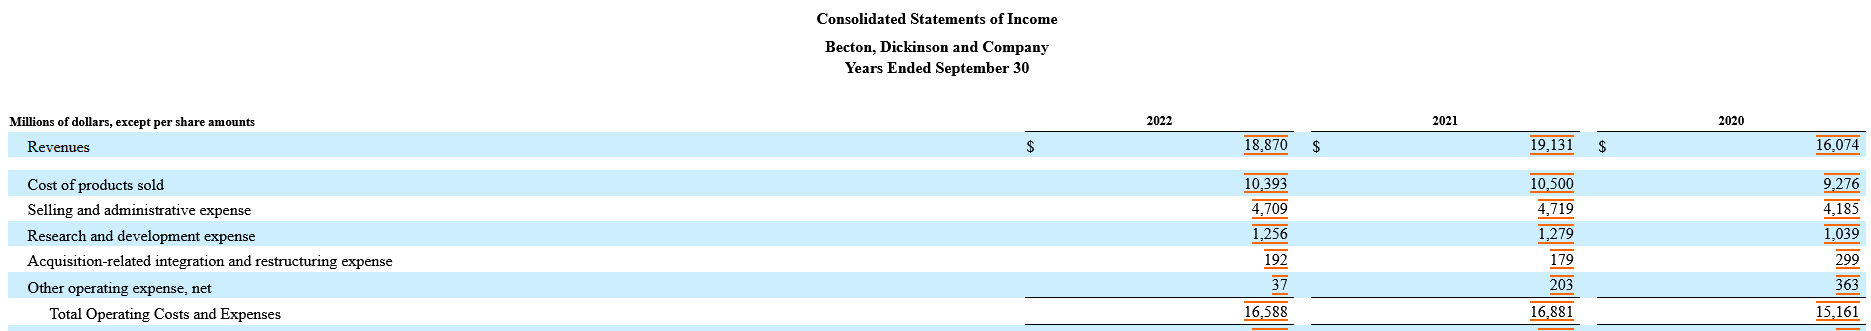
 You have Net Sales, i.e., Revenue, listed at the very top. Yet another place where different terms are used for the same concept. If we look at the income statement of another company in the space, Beckton Dickenson, their top line is called out as Revenue.
More in this series
- Why am I writing about finance?
- How to learn the financial basics about a new (to you) business
- Every scientist’s dream: Understanding financial statements
- A first look at income statements: revenue, costs and profits
- What scientists need to understand about revenue and its recognition
- Income Statement Fun: What is included in the Cost of Sales and why you should care
- How expenses and depreciation can affect the profitability of your scientific work
- Profitability: the proverbial and literal bottom line
- Using the Balance Sheet to Understand a Company’s Financial Health
- Assets: tangible, intangible, and goodwill
- Decoding Financial Health with Liabilities & Equity from the Balance Sheet
- Navigating a company’s financial condition with the cash flow statement
- The Anatomy of a Cash Flow Statement: Operating, Investing, and Financing
- Budgeting 101: Using our newly acquired financial intelligence to make sense of the budgeting process
- Making Sense of the Numbers Through Financial Ratios
- Your Company’s Quarterly Earnings Call: How to Make Sense of It All
- The “Big Five” Numbers — What Investors Care About and Why
- Net Present Value: Making the Financial Case for Advancing Scientific Projects You Care About
When revenue reporting isn’t black and white
As we saw in the examples at the top of this post, there can be a fair amount of nuance in when and how to recognize sales, and tremendous pressure to make this figure look strong. And because of this, the place where the most accounting shenanigans happen is in revenue recognition. In fact, most accounting fraud occurs in the top line, but even non-criminal bias can land a company in hot water.
A quick example of how (non-criminal) bias can creep in could be around service contracts when an instrument is sold. Let’s say customers purchase a 5-year service contract alongside an instrument. When do you recognize that income? The service at year 0 has not been rendered, so you can’t recognize all the revenue, but you can claim that most of the cost of that service contract has been in making the initial sale, so 75% of the revenue should be recognized up front. Equally legitimate would be to say that only a small percentage of the revenue should be recognized up front, because most of the cost is associated with servicing that machine down the line. It’s really a judgment call that depends on the particularities of the business.
What’s interesting is that you can even change your revenue recognition strategy, although generally it’s fairly suspicious to be doing this often (remember “consistently applied” from the last post?). If there is a change in revenue recognition strategy, it would be called out in the footnotes— another reason why it’s not a bad idea to look through them.
Another example of bias and uncertainty in revenue is the quality of the customer. Will the revenue shipped actually be paid for? Have you given special consideration to the customer (6 months to pay for example)? Have you made promises (warranty) that the product will perform down the road (a product warranty)? All of these factors can contribute to revenue uncertainty.
Depending on where in an organization you sit, scientific and technical decisions you make may impact revenue and its recognition. Are you developing a stand-alone product? Is it part of an ongoing delivery schedule? Are other services attached to it? These questions might color the response your work gets from other stakeholders in your company if they’re targeting a particular revenue goal.
Those are the highlights for revenue. In the next two posts, we’ll get into the murky realm of costs and expenses. Make sure you’re on the mailing list so you don’t miss it!
Comments
Powered by WP LinkPress